


As the Indo-Pacific undergoes a profound geopolitical and economic realignment, Vietnam has become one of the region’s most consequential partners for governments and investors alike.
In this interview with World Geostrategic Insights, Ambassador Marc Knapper, who remains based in Hanoi following his tenure as U.S. Ambassador to Vietnam, examines how Vietnam’s foreign policy has evolved from ‘bamboo diplomacy’ toward a growing emphasis on strategic autonomy, and what that means for multinational companies. He discusses the bottlenecks facing firms scaling up in Vietnam, emerging opportunities in international financial services, energy and healthcare, the role Europe can play in the region, and why upholding international law in the South China Sea matters to all trading nations.
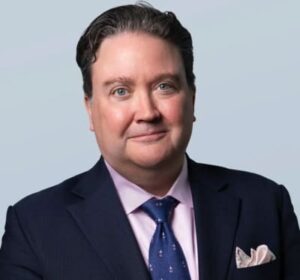
Ambassador Marc Knapper is CEO of Knapper Global Advisors, a strategic advisory firm headquartered in Hanoi that counsels companies from the United States, Europe, Japan and Korea on political risk, regulatory frameworks and market entry across the Indo-Pacific. He is also an advisor to the Vietnam International Financial Center in Ho Chi Minh City. His 33-year career at the U.S. Department of State culminated in his tenure as U.S. Ambassador to Vietnam from 2022 to 2026, during which the two countries elevated their relationship to a Comprehensive Strategic Partnership. Earlier, he was Deputy Assistant Secretary of State for Japan and Korea and Chargé d’Affaires at the U.S. Embassy in Seoul, with other assignments in Tokyo, Baghdad and Washington. Ambassador Knapper is a summa cum laude graduate of Princeton University.
Q1 – How has your transition from government to advising companies through Knapper Global Advisors, while remaining based in Hanoi, shaped your perspective on Indo-Pacific dynamics? How do the risk priorities of multinational companies differ from the strategic calculations of governments in the region?
A1 – What has struck me most since leaving government is how similar the two worlds are, not how different. People assume a diplomat and an investor see the region through very different lenses. In my experience, they are asking the same fundamental question: can I rely on this partner, and will that still be true in five years?
Both depend on trust built over time, through relationships rather than transactions. Both reward people who understand local history, culture and how decisions are actually made, not just how they appear on paper. And both have learned the same lesson about risk: the danger is rarely the headline you read in the morning. It is the slow erosion of predictability, when rules, commitments or priorities shift without warning. A government judging a partner’s reliability and a company judging where to build its next factory are doing much the same analysis.
That is why the transition has felt natural. The skills that served me in Seoul, Tokyo and Hanoi, listening carefully, reading intentions and building trust across cultures, are exactly what American, European, Japanese and Korean companies need as they navigate the region. I still live and work in Hanoi. The job has changed, but the work is remarkably familiar.
Q2 – During your tenure in Hanoi, the bilateral relationship between the United States and Vietnam was elevated to a Comprehensive Strategic Partnership. As Washington and Beijing navigate a prolonged era of strategic competition, how resilient do you consider Vietnam’s traditional foreign policy framework of “bamboo diplomacy” to be against systemic external pressures?
A2 – “Bamboo diplomacy” remains a popular shorthand abroad, but in Hanoi today you hear it less. The emphasis has shifted toward strategic autonomy, and toward foreign policy as an engine of what Vietnam calls its new era of national development. Vietnam’s leadership now frames its approach in terms of strategic autonomy and respect for international law rather than bamboo.
The core logic is unchanged, and I would argue it is one of the more resilient approaches in the region. Vietnam will not choose sides. Over the past few years it has elevated relationships with the United States, China, Japan, Korea, India, Australia, France, the United Kingdom and others, often in quick succession. That is not hedging out of indecision. It is a deliberate strategy of making many partners invested in Vietnam’s success. What has changed is the tone: more confident, more ambitious, and more explicitly tied to economic growth.
The upgrade to a Comprehensive Strategic Partnership with the United States fits within that framework rather than departing from it. Our partnership was built on respect for Vietnam’s independence, sovereignty and political system, and it was never premised on Vietnam distancing itself from anyone else.
Europe is part of the same picture. The EU–Vietnam Free Trade Agreement, in force since 2020, and Vietnam’s strategic partnerships with European countries give Hanoi another set of partners who are not asking it to choose. From where I sit in Hanoi, that is exactly why Europe is valued here: it widens Vietnam’s options rather than narrowing them.
The test ahead is less about whether the approach holds than about how much room it leaves. As trade, technology and supply chains become more contested, every partner will ask more of Vietnam. My sense is that Hanoi understands this well. Its greatest asset is the trust it has built across so many relationships: as a reliable place to invest, a constructive voice in ASEAN, and a partner that keeps its commitments.
Q3 – Vietnam has emerged as a cornerstone of the U.S. strategy to build resilient, friend-shored semiconductor and high-tech supply chains. From a commercial standpoint, what do you identify as the most critical structural bottlenecks, whether in logistical infrastructure, regulatory framework, or human capital, currently facing multinational firms looking to scale operations in Vietnam?
A3 – I would point to three, and Vietnam’s leadership is working on all of them.
The first is energy. Advanced manufacturing, and especially semiconductors and data centers, needs power that is abundant, stable and increasingly clean. The power shortages of 2023 were a wake-up call. Expanding transmission, adding generation and creating workable mechanisms for companies to buy renewable power directly are now real priorities. Investors watch this more closely than almost anything else.
The second is talent. Vietnam has a young, hardworking and well-educated population, but the number of engineers with hands-on experience in chip design, packaging and testing is still small relative to demand. Partnerships between companies, universities and governments, including American ones, can close that gap faster than any one actor alone.
The third is the pace and predictability of administrative processes: permits, customs and the consistent application of rules across provinces. The current reform push, including the streamlining of government and the creation of new financial and investment frameworks, is encouraging.
European companies, many of which already benefit from the EU–Vietnam Free Trade Agreement, raise the same issues. Europe is also well placed to help solve them. It brings deep expertise in offshore wind, grids and vocational training, and it is a partner in Vietnam’s Just Energy Transition Partnership.
None of these are reasons to avoid Vietnam. They are the to-do list of a country that has already proven it can attract world-class manufacturing and now wants to move up the value chain.
Q4 – Beyond the highly publicized hardware and technology manufacturing sectors, what under-the-radar economic segments in Southeast Asia do you advise global investors to monitor closely through your work at Knapper Global Advisors?
A4 – Three areas stand out to me.
First, international financial services. Domestic banking and brokerage in Southeast Asia have grown impressively, but the region is still short of the international-standard services that global capital expects: cross-border fund management, institutional investment, reinsurance, trade and project finance, and trusted mechanisms for resolving commercial disputes. That gap is exactly what Vietnam’s international financial center, along with its push to upgrade its stock market, aims to fill. (In the interest of full disclosure, I serve as an advisor to the Vietnam International Financial Center in Ho Chi Minh City.) These developments are getting less attention than factories, but they could matter just as much.
Second, the energy transition and the infrastructure behind it: grids, storage, LNG-to-power, and the services that support them. Every manufacturing and digital ambition in the region runs into energy sooner or later, so the companies that solve that problem will be in demand for a long time.
Third, healthcare and education. Rising incomes and aging populations, including in Vietnam, are changing the region’s health needs. The fastest-growing challenges are now the conditions typical of middle-aged and more affluent societies, such as stroke, heart disease and diabetes. That is driving demand for hospitals, medical devices, pharmaceuticals, preventive care and the skilled workforce to deliver them. These sectors are less glamorous than semiconductors, but they are deeply tied to how societies in the region will live and work.
European firms are particularly well placed in all three, given their strengths in renewable energy, insurance and asset management, pharmaceuticals and medical technology. In each case, success depends on understanding local regulation and building trusted local partnerships. That is where patient investors tend to outperform.
Q5 – The South China Sea persistingly serves as a critical flashpoint for regional security, directly impacting maritime sovereignty. In what ways might the comprehensive strategic alignment between Washington and Hanoi recalibrate Vietnam’s asymmetric deterrence capabilities? Furthermore, how can Hanoi effectively leverage this heightened defense cooperation to counter regional revisionism without inadvertently provoking an adversarial containment response or economic retaliation from Beijing?
A5 – Let’s be clear about where the instability comes from. It is not from Vietnam, and it is not from the United States. It comes from sweeping maritime claims that an international tribunal rejected in 2016, from artificial islands turned into military outposts, and from the daily harassment of fishermen, survey vessels and energy projects. Coercion that stays just below the threshold of conflict is still coercion.
I would also push back on the premise that Vietnam needs Washington to recalibrate anything. Vietnam has defended its sovereignty for a very long time, and it decides its own defense posture. What the United States can offer is support for capabilities Vietnam has chosen to build: maritime domain awareness, coast guard and law enforcement capacity, and training. America has already transferred three former U.S. Coast Guard cutters to Vietnam, and that kind of cooperation matters more than headlines about alliances that Vietnam does not seek.
The most effective deterrent is not a weapons system. It is raising the cost of coercion: documenting incidents openly, grounding every position in UNCLOS, and standing with other countries that share the same interest in lawful, open seas.
That is where Europe comes in. A large share of Europe’s trade with Asia passes through these waters. When European navies sail there and European governments speak up for international law, the message is that this is not a U.S.–China contest. It is a question of whether the rules apply to everyone.
As for provoking Beijing, the lesson of the past decade is that restraint by others has not bought restraint in return. Vietnam manages its relationship with China carefully and wisely, and it will continue to. But calm, lawful firmness, backed by many partners, is not provocation. It is the best guarantee of stability.
Q6 – Given your vantage point spanning Washington and Hanoi, what should the United States prioritize to deepen its economic and security partnerships with ASEAN member states?
A6 – First, show up consistently. In Southeast Asia, presence is policy. Regular visits by senior leaders, steady participation in ASEAN meetings, and ambassadors and diplomats on the ground send a signal that no communiqué can match.
Second, treat economics and security as two sides of the same partnership. ASEAN governments want investment, trade and technology that create jobs and raise incomes, and they also want partners who help keep the region stable and the sea lanes open. Each reinforces the other: secure waters and resilient supply chains attract investment, and deep economic ties give everyone a stake in stability. American companies are already among the largest investors in the region, and policies that support them, through financing tools, workforce partnerships and clear, stable trade terms, are as much a part of U.S. strategy as our defense cooperation.
Third, respect each country’s choices. ASEAN members do not want to be asked to pick sides. The United States does best when it offers to be the most reliable and valuable partner, not the exclusive one.
The same applies to Europe. Seen from Hanoi, the United States and Europe are complementary partners, not competitors. When Washington and Brussels coordinate on infrastructure financing, the energy transition and technology standards, the combined offer to ASEAN is far stronger than either alone.
Finally, invest in people. Educational exchanges, the Young Southeast Asian Leaders Initiative, Fulbright and English-language programs have built a generation of leaders across the region who know and trust America. Those relationships are among our greatest long-term assets, and they are worth sustaining.
Ambassador Marc Knapper – CEO of Knapper Global Advisors.